


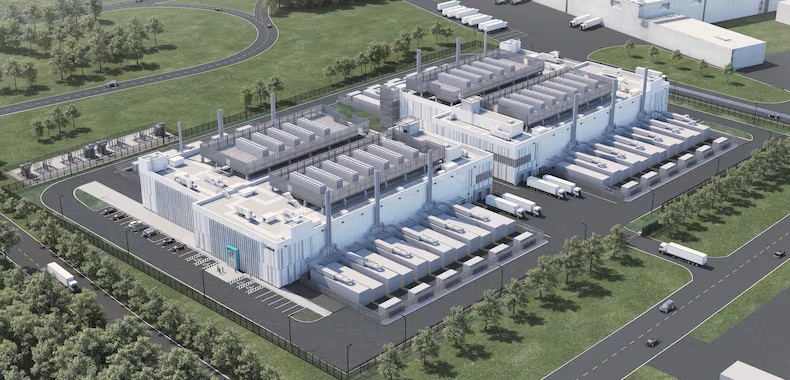
The global data center market is experiencing an unprecedented boom, driven by a surge in demand for computing power, the rapid development of artificial intelligence, cloud services, and the accelerating digitalisation of economies. Against this backdrop, Europe is gaining strategic importance, supported by EU policies promoting digital transformation and green energy. Within the region, Poland is emerging as a key hub, attracting infrastructure investors and cloud service providers.
Global data center boom – multibillion-dollar investments
According to the latest Spectis report, "Data center construction market in Poland 2026–2031", the coming years will see a wave of spectacular projects launched by the world’s biggest tech players.
Following an investment of over USD 14bn in Scale AI, Meta is continuing its aggressive expansion in the AI infrastructure segment. The company has announced plans to allocate hundreds of billions of dollars more to expand data centre campuses in the United States and Europe. The total value of future commitments related to the development of AI infrastructure is currently estimated at around USD 183bn.
Amazon Web Services remains the largest investor in the data centre sector. The company is developing new cloud regions in Asia, South America, and Europe, with its annual capital expenditure already exceeding USD 100bn. At the same time, Microsoft and Google are intensifying the construction of new hyperscale facilities, focusing primarily on infrastructure designed to support artificial intelligence models. Investments in Europe, including Central and Eastern Europe, are also gaining significance.
After surpassing USD 200bn in new investments in the data centre sector in 2024, the scale of spending by major technology companies continues to grow rapidly. Amazon, Microsoft, Google, and Meta have announced that their combined capital expenditure in 2026 could exceed USD 700bn. A significant portion of these funds will be allocated to the development of AI infrastructure, including the construction of new data centres, as well as the procurement of servers, network, and power infrastructure.
Examples of hyperscale data center projects
Among the key developments by major data centre owners is Meta’s hyperscale campus in Jeffersonville, Indiana. Construction of the facility began in 2024 and is scheduled for completion in 2026. The campus, spanning nearly 65,000 sqm, is being built by ACS Group through Turner Construction Company.
Another notable project is the Citadel Campus by Switch, located in Tahoe Reno, Nevada - currently the largest data centre in the world, with an area of approximately 120,000 sqm. Switch is managing the design and construction process in-house, with no external general contractor disclosed.

Europe in the spotlight of global tech giants
Europe is fast becoming one of the world's key data center development hotspots, attracting both major tech companies and infrastructure investors. The strongest growth is seen in Germany, Ireland, the Netherlands, and the Nordic countries, where low-cost renewable energy and favourable environmental regulations support hyperscale expansion.
Frankfurt, Dublin, and Amsterdam remain leaders in terms of scale and infrastructure maturity. However, interest in Central and Eastern Europe — especially Poland, the Czech Republic, and Hungary — is on the rise, driven by increasing demand for local computing capacity and competitive costs.
The European Union is actively driving the development of the data center sector through policies supporting digital transformation and clean energy. This encourages companies like Microsoft, Amazon Web Services, and Google Cloud to choose Europe as a preferred location for future investments.

Poland’s growing role in the European data center market
Given the upbeat global outlook, we took a closer look at Poland’s data center construction market - both in terms of ongoing and planned projects, and key development drivers.
Poland’s market is growing rapidly, driven not only by domestic demand but also by the presence of global tech giants. These players are ramping up their investments, drawn by Poland’s strategic location, growing demand for digital services, and improving infrastructure.
Microsoft is expanding its data center campus near Warsaw, while Google is scaling up infrastructure for Google Cloud in the capital, positioning Poland as a critical access point in Central and Eastern Europe.
Other key investors include:
- Equinix
- Vantage Data Centers
- EdgeConneX
These companies are pursuing large-scale developments primarily in the Warsaw area.
The scale and pace of these projects clearly show that Poland is emerging as a major data center hub in the region.
In parallel, further investments are being prepared, which could significantly increase the capacity of the Polish market in the coming years. Data centre projects are currently being developed by entities such as NASK, Fortis Hub, Budimex Data Centers, Baltic Data Center Campus, Hyperscale Data Center Bełchatów, and Switch Data Centers.

Public support for data center development
In addition to private sector funding, key growth drivers in the coming years will include public co-financing under several national and EU initiatives, such as:
- European Funds for Infrastructure, Climate and Environment (FEnIKS)
- AI Continent Action Plan
- InvestAI initiative
This support will facilitate the construction of state-of-the-art data centers and upgrades to existing facilities, further strengthening Poland’s appeal for IT infrastructure providers.
Sample data centers in Poland
Below are examples of selected data centers currently operating in Poland:
-
Microsoft WAW01 and WAW02
Location: Warsaw
Operator: Microsoft
Type: Hyperscale cloud center
Part of the Microsoft Azure global infrastructure serving Central Europe
-
Orange Warsaw Data Hub
Location: Warsaw
Operator: Orange Polska
Type: Colocation center
A key data hub for the telecom sector
-
Vantage Data Centers WAW1
Location: Warsaw
Operator: Vantage Data Centers
Type: Hyperscale colocation center
Initial phase delivered by Porr, currently under expansion
-
Atman Data Center Warsaw-1 (WAW-1)
Location: Warsaw
Operator: Atman
Type: Colocation center
Modern facility with security certifications
-
Equinix WA4x
Location: Warsaw
Operator: Equinix
Type: Hyperscale colocation center
Part of the global Platform Equinix network
-
Polcom Data Center Alwernia
Location: Alwernia
Operator: Polcom
Type: Regional data center
Strategic location near Kraków
-
Beyond.pl Data Center 2
Location: Poznań
Operator: Beyond.pl
Type: Hyperscale colocation center
Recognised in the financial and AI/ML sectors
The full list of around 150 data centers in Poland, along with in-depth market analysis, growth forecasts, and profiles of key investors and contractors, is available in the Spectis report "Data center construction market in Poland 2025–2030".
Data center delivery models
Two main delivery models are used when planning and building new data center facilities:
Greenfield – building from scratch
Construction on undeveloped land allows the facility to meet the latest standards in energy efficiency, security, and future expansion. Advantages include:
- Optimised layout of technical infrastructure
- Maximised energy efficiency (PUE)
- Flexibility in planning future expansions
- Compliance with the latest industry standards
Brownfield – repurposing existing buildings
Redeveloping existing structures, often former office buildings, allows for quicker commissioning and cost optimisation. Advantages include:
- Shorter project timelines
- Use of existing structural infrastructure
- Lower initial investment costs
- Potential for urban locations
Key drivers of market growth
In the coming years, Poland’s data center market will be supported by:
- Rapid growth of edge computing and the need for local data processing, driving demand for smaller, distributed facilities closer to end users
- Entry of major global players, including hyperscalers and specialist operators like Google and Microsoft, expanding the investment scale
- A shift toward subscription-based IT services, increasing demand for colocation capacity
- New cooling technologies (e.g. liquid cooling, adiabatic systems) enabling more energy-efficient operations
- The relatively low share of building costs compared to the technical equipment, creating opportunities for Polish contractors and suppliers to participate in high-margin, top-tier projects
- Establishment of local hyperscaler zones (e.g. new Azure and Google Cloud regions) spurring additional infrastructure investment
Barriers to market development
Key challenges that may hinder data center development in Poland include:
- Strong regional competition — countries like the Czech Republic, Germany, and the Nordics offer better incentives such as cheaper green energy and tax breaks
- Volatile and unpredictable energy prices in Poland, which may impact profitability
- Growing price pressure as customers push for cheaper cloud and colocation services, squeezing operator margins
- Rising number of cyberattacks on critical infrastructure, requiring growing investment in physical and digital security
- Rapid technology shifts (e.g. processor and server upgrades), leading to faster infrastructure obsolescence and increased financial risk
- Limited grid connection capacity and delays in expanding the power network may stall new projects
- High energy demand and geopolitical risks could undermine Poland’s attractiveness for hyperscale investments
- Increased need for efficient cooling solutions during prolonged heatwaves, which may drive up operating costs
To learn more or download a sample report, visit our store:
Methodology note
For the purposes of the report, the term data center construction market refers to the design and delivery of full-scale data center buildings along with technical interior fit-outs. This includes construction and renovation works, as well as the execution of specialised server rooms in compliance with industry standards. The analysis covers both greenfield and brownfield projects, and various types of facilities: colocation, hyperscale, private, and edge data centers.

